

myFICO: FICO Credit Check
FICO
- 4.3
- 4.11K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
myFICO: FICO Credit Check Pros and Cons
Pros
- Comprehensive credit reports available.
- Real-time credit monitoring alerts.
- Easy-to-navigate user interface.
- Access to multiple FICO scores.
- Educational resources on credit scores.
Cons
- Subscription required for full features.
- Limited free features available.
- Complex data can overwhelm novices.
- Occasional delays in report updates.
- Some features are US-specific.
 Analysis by All-app
When I’m trying to make a financial decision, I want to know what is happening with my credit without having to turn it into a second job. myFICO: FICO Credit Check is a finance app from FICO that puts credit information within reach, with a focus on scores and reports. It’s free to install, rated for Everyone, and has a 4.3 average from around 11,000 ratings. That makes it easy to try, though the most useful question is whether its detail and layout fit the way you actually manage money.
Making credit information easier to use
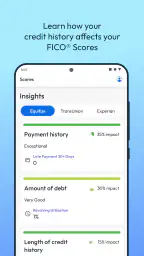
My first impression is that the app is aimed at people who want more than a score by itself. A number can be reassuring or alarming, but without context it doesn’t tell me what to do next. The report and score information are more helpful when I use them to spot a change, understand what may be influencing the score, and decide whether I need to investigate further. That makes this more of a monitoring and learning tool than a quick score lookup.
Readability and navigation
Credit reports can feel dense even when they are presented clearly, so I appreciate an app that organizes the information instead of expecting me to interpret a wall of financial language. In my experience, the useful habit is to check one section at a time: first the overall score, then the report details that explain it. That is less tiring than trying to absorb everything in one sitting, particularly if you are new to credit terminology.
The app has a 4.0.13.1 version and has been available since August 18, 2015. FICO is a familiar name in credit scoring, which gives the app a clear purpose: helping users follow information connected to their credit profile rather than offering a general-purpose budget or banking dashboard. It has over one million installs, and the large number of user ratings suggests that credit monitoring is a regular need for many people, not just something they look up when applying for a loan.
Motor and sensory considerations
I would approach any credit app at a comfortable pace, especially when entering personal information or reviewing a report. The subject matter itself calls for attention: a rushed tap or a skimmed line can make it harder to distinguish an unfamiliar entry from a genuine concern. Taking a moment to read each screen and pausing before acting on an alert is a sensible way to use it.
If you find financial language difficult to process, the app’s explanatory approach may be more approachable than a bare score, but it still asks you to engage with details that can be unfamiliar. I’d keep a note of terms or questions as I go rather than trying to memorize every factor at once. Anyone who relies on particular text-size, contrast, screen-reader, or input settings should check how the current app works with those settings on their own device before relying on it for routine monitoring.
Situational access
A practical moment to use it is before a major financial conversation. If I’m considering a mortgage, car loan, or credit card, I can review my credit information in advance and arrive with a better sense of what I need to ask. That does not replace a lender’s decision or guarantee a particular offer, but it can help me avoid going into the conversation completely blind.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
It can also fit into a quieter monthly routine. I might review the report when I have time to focus, then return to the app only if a change or alert gives me a reason. That approach is more useful than repeatedly opening a credit app out of worry. Credit scores can move for reasons that are not obvious from a quick glance, so I try to treat a notification as a prompt to investigate rather than proof that something is wrong.
What to expect from monitoring
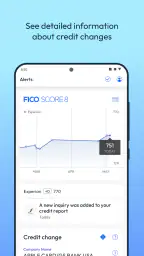
Alerts are most valuable when they lead to a concrete check: compare the report entry with your own records, confirm whether you recognize the account or activity, and then decide what to do. I would not assume every alert calls for immediate action, nor would I rely on a phone notification as my only way to catch a problem. A deliberate report review gives more context than a headline or score change alone.
There is also a useful distinction between keeping an eye on your credit and actively improving it. Seeing the components of a score can help me understand what might be affecting it, but an app cannot make payments, correct a report entry, or choose a borrowing strategy on my behalf. I see the value here as turning a vague concern into a more specific question to research or discuss with a financial professional.
Where it fits among credit tools
Compared with a bank app that includes a free score as one small feature, a dedicated credit-monitoring app is a better fit when I want to spend time with the report itself and follow changes. A basic score-checking service may be enough if all I need is an occasional snapshot. On the other hand, someone who wants a full household budget, spending categories, and bill tracking will probably be better served by a personal-finance app built around those jobs.
It is worth being clear about the scope before settling into a routine. The store summary emphasizes a FICO Score and an Equifax report, while the published app description also refers to scores from three major bureaus. Those are not interchangeable promises about every screen or every plan, so I would check what is available to me inside the app before making it my only source. Credit products can differ in which bureau information they show and how often it is refreshed; when a decision depends on a specific report, I would verify that the report I need is the one I’m reviewing.
Good habits for a useful review
For a more meaningful check, I’d compare like with like: note the date, look at the same score type when possible, and focus on changes rather than treating every point movement as a crisis. If I’m preparing for a loan application, I’d review the report early enough to follow up on an unfamiliar detail instead of waiting until the day I apply. This is a small workflow change, but it turns monitoring into preparation rather than last-minute reassurance.
I’d also separate normal curiosity from a need for action. A report is personal financial information, so I would open it somewhere I can concentrate and avoid discussing sensitive details where other people can see my screen. If another person helps manage finances, it is still better to share only what is needed and to keep account access under the account holder’s control. These habits matter regardless of how convenient an app feels.
Remaining barriers and trade-offs
The main friction is that credit monitoring can create more questions than it answers at first. A score is easy to notice; understanding the factors behind it takes patience. If you only want a quick number, a simpler service may feel less demanding. If your finances are already stressful, frequent checking may add anxiety without changing what you can do that day. I would choose a review schedule that supports a real decision rather than checking constantly.
There is also a cost boundary to keep in mind. The app is free to install, but the original review notes that some premium features require payment. I would start with the access available without upgrading, identify the specific information I still need, and only then decide whether a paid option is worthwhile. That avoids paying for depth I may not use. The app’s overall rating is positive, but ratings cannot tell me whether a particular plan or interface will suit my circumstances.
For readers with access needs, the most important practical question is not whether an app claims to be inclusive, but whether its text, navigation, and controls work with the tools they personally use. I would test the screens I expect to visit most—sign-in, score overview, report details, and alert review—before making it part of an essential routine. If those screens are difficult to operate, a different way of accessing credit information may be more dependable.
Who is likely to benefit
I’d recommend giving it a look if you are preparing for a major borrowing decision, want to understand your credit profile beyond a single number, or prefer to keep monitoring information in one dedicated place. It is also a reasonable starting point for someone learning how credit reports relate to scores, as long as they are willing to read the details and verify anything that does not make sense.
I would skip it if you only need an occasional score check and already have a simpler tool that answers that question, or if you are looking for a full budgeting system. I would also avoid relying on any single app as the final authority when correcting a report issue or making a lending decision. Use it to notice and investigate; confirm important details through the relevant credit-reporting or financial channel.
Ever wondered just how your credit score is doing in the grand scheme of things? I’ve recently taken the plunge into the world of credit monitoring with myFICO: FICO Credit Check, and I’m here to spill the beans on what it’s like to use this app. It's one of those tools that promises to keep you in the loop about your credit information, and well, who wouldn't want to be in the know?
Getting Started with myFICO
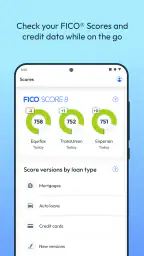
First off, setting up myFICO was a breeze. The app guides you through the setup with an easy-to-follow process. Once you’ve got it all set up, the app offers a wealth of information at your fingertips. You can view your credit score from all three major credit bureaus – Experian, TransUnion, and Equifax. And let’s be honest, knowing your score from all three is like having the Holy Grail of credit scores.
Features That Stand Out
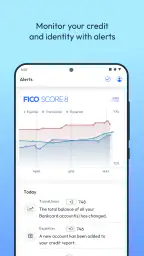
One of the standout features for me is the real-time credit monitoring. This isn’t just your average "check your score once a month" gig – no, it’s much more proactive. You’ll get alerts for any significant changes to your credit report, which is super handy if you’re someone who likes to stay on top of things.
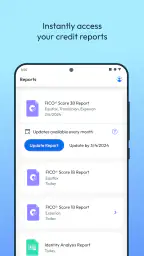
Another feature worth mentioning is the detailed credit report analysis. The app doesn’t just give you a number and send you on your way. It breaks down the components of your credit score, helping you understand what’s affecting it. This is gold if you’re trying to improve your score or just maintain a healthy one.
Why You Might Love It
If you’re like me and have always been a bit clueless about how credit scores work, this app is a game changer. It’s educational and doesn’t leave you feeling overwhelmed. Plus, having all your credit information in one place is incredibly convenient. No more logging into different sites or trying to decipher complicated reports – it’s all here, neatly organized and easy to understand.
A Few Quirks
Of course, no app is without its quirks. While the app is pretty comprehensive, the premium features do come at a price. If you’re someone who wants to dive deep into their credit health, you might find yourself considering an upgrade to access all the bells and whistles. But hey, if you’re serious about your credit, it might just be worth it.
Another thing to keep in mind is that while the app is user-friendly, the sheer amount of information can be a tad overwhelming at first. But, with a little patience, you’ll get the hang of it.
To wrap it up, the app is a powerful tool for anyone looking to get serious about their credit health. It’s like having a credit advisor in your pocket, ready to help you make sense of the numbers. Whether you’re looking to buy a house, a car, or just want to keep tabs on your financial health, this app is worth checking out.
Frequently Asked Questions
What is myFICO: FICO Credit Check and how does it work?
myFICO: FICO Credit Check is an application designed to help users monitor their credit scores and understand their financial health. It provides access to your FICO scores, credit reports, and alerts for any changes. By using this app, users can make informed decisions regarding their credit and financial planning, boosting their overall financial literacy.
Is myFICO: FICO Credit Check secure to use?
Yes, myFICO: FICO Credit Check is secure to use. The app employs advanced encryption technology to protect your personal and financial information. Additionally, it follows stringent security protocols to ensure data privacy, making it a reliable choice for users concerned about their sensitive information's safety.
How often are credit scores updated in the myFICO app?
Credit scores in the myFICO app are updated regularly, typically every month. This frequency allows users to stay abreast of their credit status and any changes that might affect their financial standing. Regular updates are crucial for effective credit monitoring and financial planning.
What features does myFICO offer beyond credit score monitoring?
Besides credit score monitoring, myFICO offers a range of features to enhance user experience and financial management. These include detailed credit reports from all three bureaus, identity theft protection, and access to educational resources about credit management. The app also provides alerts for any significant changes to your credit profile.
Does myFICO: FICO Credit Check offer customer support if I encounter issues?
Yes, myFICO: FICO Credit Check offers robust customer support to assist users with any issues they might encounter. Users can access support through multiple channels, including email, phone, and a comprehensive help center within the app. This ensures that all user queries and concerns are addressed promptly and effectively.


